Car Insurance Pakistan: What's Covered and Excluded?
Think comprehensive insurance covers everything? In Pakistan, exclusions, reduced payouts and policy breaches can leave you with costly repair bills.
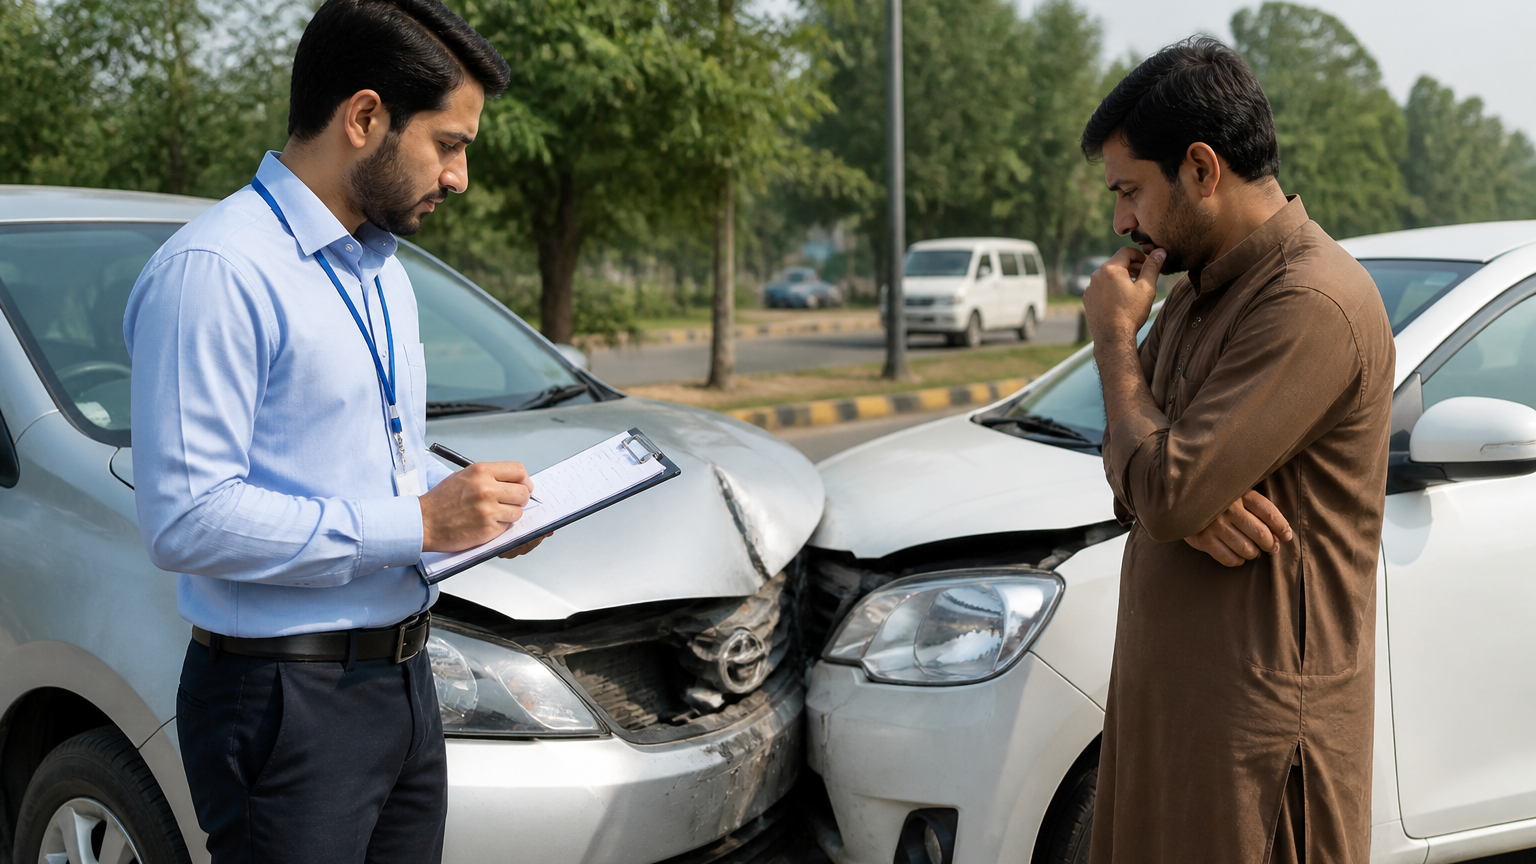
Table of Contents
- What comprehensive cover usually pays for
- The common exclusions that can hurt a claim
- Even approved claims can be cut down
- Takaful is not always broader
- What owners should ask before buying
- The practical takeaway
- Explore DrivePK services
Many Pakistani car owners think comprehensive insurance means every repair will be paid for. That is not how most policies work. A comprehensive plan can still leave you with a big bill if the damage falls under an exclusion, if the claim is reduced, or if you break the policy rules.
That is why the fine print matters. The word comprehensivegives wide protection, but it does not mean unlimited protection.
What comprehensive cover usually pays for
A typical comprehensive motor policy in Pakistan usually covers accidental damage, including crashes caused by the driver’s own mistake. It can also cover theft and snatching, fire and explosion, and flood damage if the policy clearly includes natural disasters.
It may also cover malicious damage caused by other people and third-party liability, which is your legal responsibility for injury or damage to others, within the policy limits.
But the policy schedule and exclusions always matter more than the general idea of “full cover.”
The common exclusions that can hurt a claim
There are several reasons an insurer may reject or reduce a claim. One of the most common is wear and tear. Normal ageing, routine maintenance, engine failure, brake wear, or gearbox trouble are usually not covered.
Tyres and batteries are another weak point. They are often excluded unless they are damaged in the same insured accident.
Claims can also fail if the driver was under the influence of alcohol or drugs, or if the person behind the wheel did not have a valid licence. Some policies also limit who may drive the car.
Racing, motorsport, and certain off-road activities are often outside cover. So are unauthorised commercial uses, such as ride-hailing or paid pick-and-drop work in a private car.
Other common exclusions include intentional damage, false claims, undeclared modifications, personal items stolen from inside the car, and indirect losses such as lost income or taxi fares while the car is in the workshop.
Late reporting can also create trouble. If the owner delays the claim, hides key details, or starts repairs before inspection, the insurer may dispute the case.
Even approved claims can be cut down
Some owners are surprised when a claim is accepted but the payout is still smaller than expected.
Depreciation is one reason. If a part is replaced, the insurer may deduct value for age and use. For example, a headlight worth Rs. 100,000 may not be paid in full.
A deductible is another deduction. If a repair bill is Rs. 80,000 and the deductible is Rs. 10,000, the insurer may pay Rs. 70,000 before any other cuts.
Settlement can also depend on agreed value and market value, especially in theft or total-loss cases. If a car is underinsured, compensation can also fall short.
Takaful is not always broader
Motor takaful works on a Shariah-compliant protection model, but owners should not assume it gives wider cover than conventional insurance. Exclusions, deductibles, depreciation rules, and claim conditions can still be similar.
What owners should ask before buying
Before signing, ask about floods, riots, strikes, terrorism, family-driver cover, depreciation rates, workshop choice, genuine parts, commercial use, and reporting deadlines. Ask for written clarity on anything important.
The practical takeaway
The safest move is simple: read the policy before an accident, not after one. The cheapest premium is not always the best choice if it leaves key risks uncovered.
Explore DrivePK services
Buying or selling a vehicle? Explore DrivePK services, including car inspection, Sell It For Me and Featured Listings, and choose the option that fits your needs.
For more updates, visit DrivePK.com
Tags
Share this article
About the Author
Dr Khan
Automotive Expert & Content Strategist
Comments (0)
Login Required
You need to be logged in to comment on this article.
No comments yet. Be the first to share your thoughts!
Related Articles
پاکستان میں کار انشورنس: کیا شامل ہے اور کیا خارج ہے؟
کیا آپ سمجھتے ہیں کہ جامع انشورنس ہر چیز کا احاطہ کرتی ہے؟ پاکستان میں مستثنیات، کم ادائیگیاں اور پالیسی کی خلاف ورزیاں آپ کو بھاری مرمت کے اخراجات میں مبتلا کر سکتی ہیں۔
Pakistan میں Toyota Corolla Grande کی چلانے کی لاگت
ایک Corolla Grande کی لاگت اس کی ظاہری قیمت سے کہیں زیادہ ہو سکتی ہے: صرف ایندھن پر تقریباً Rs25.30 فی کلومیٹر، Rs42,167 ماہانہ اور Rs506,000 سالانہ خرچ آ سکتا ہے، اگر ڈرائیونگ مخلوط ہو۔